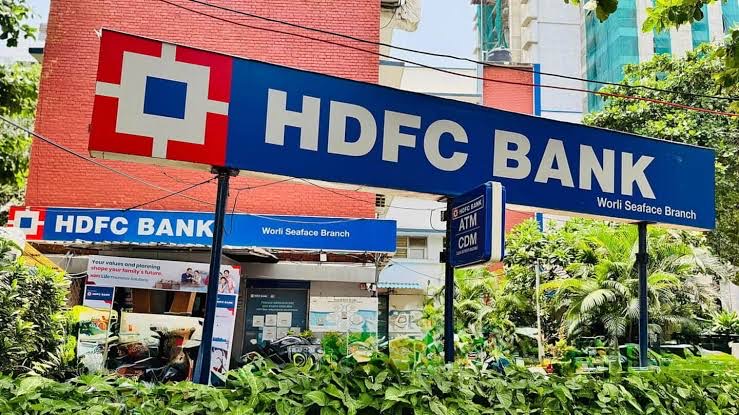
HDFC Bank reported a 4.7 percent year-on-year rise in standalone net profit to Rs 19,510 crore for the second quarter of FY27, the three months ended 30 September 2026. The results were announced on Saturday, 17 October, and broadly met market expectations. Net interest income, the difference between what the bank earns on loans and pays on deposits, grew 9.7 percent to Rs 34,620 crore. Asset quality improved, with the gross non-performing asset ratio at 1.11 percent. The numbers show a lender still growing its loan book much faster than its profit, which is the main question investors are asking about India’s largest private bank. Standalone figures cover the bank alone, while the consolidated figures also include its subsidiaries, and the two moved at slightly different speeds this quarter. The net interest margin was 3.16 percent of total assets and 3.32 percent of interest-earning assets, and the net NPA ratio was 0.37 percent.
The case that the quarter was a good one rests on balance-sheet growth and asset quality. Gross advances grew 16.3 percent year on year to about Rs 32.2 lakh crore, and deposits grew 18.8 percent, so the bank is gathering funds faster than it is lending them. The gross NPA ratio improved to 1.11 percent from 1.17 percent in the previous quarter and 1.24 percent a year earlier, while the net NPA ratio stood at 0.37 percent. CASA deposits, the low-cost current and savings balances, made up 31.6 percent of the total. On a consolidated basis, Kotak Neo reports profit of Rs 20,700 crore, up 5.6 percent, which means the wider group is growing a little faster than the bank alone.
The counter-argument is that profit growth of 4.7 percent is thin next to loan growth of 16.3 percent and deposit growth of 18.8 percent. Net interest income rose only 9.7 percent, well below balance-sheet growth, and the net interest margin stood at 3.16 percent of total assets, down from 3.26 percent in the previous quarter according to one report. In other words, the bank is adding assets without adding proportionate profit. That gap is also visible next to ICICI Bank, which reported consolidated profit growth of 22.3 percent for the same quarter. Sources also differ slightly on the headline profit, with one report giving Rs 19,610 crore, so readers should check the bank’s own filing for exact figures.
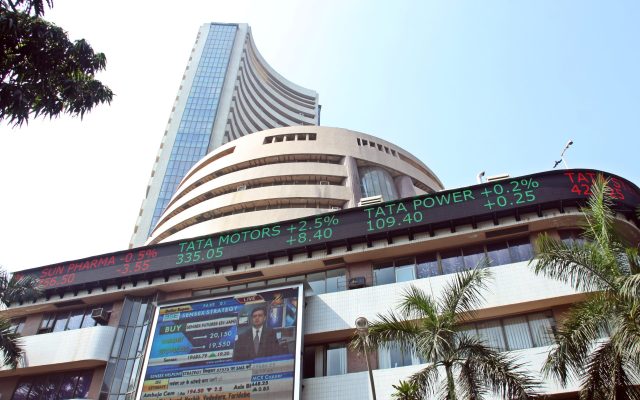
The result matters beyond the bank because HDFC Bank is the largest private lender in the country and a heavy weight in the Sensex and Nifty. Its margin and deposit trends are a guide to how costly money is for the whole banking system, and its loan growth is a guide to credit demand from households and businesses. With markets already nervous about elevated crude prices and foreign selling, a stable lender with improving asset quality is a source of reassurance.
HDFC Bank delivered cleaner books and strong balance-sheet growth in the quarter, but profit growth of 4.7 percent leaves a question over margins. The next few quarters will show whether the bank can turn rapid deposit and loan growth into faster earnings.
Leave a Reply