India's festive season is normally the busiest stretch of the year for smartphone makers, a period in which sales events, discounts and Diwali shopping pull millions of buyers into stores and onto e-commerce apps. This year, the numbers tell a different story. According to research firm Counterpoint, smartphone sales during the festive season, which ran from October 8 to November 10, collapsed by an estimated 22 percent year-on-year, as rising memory costs pushed phone prices to new highs and buyers held back their purchases. The Hindu reported the findings on Friday, November 20, 2026.
The size of the fall was a surprise even to the people who track the market. Counterpoint's findings note that the decline was "much steeper" than its pre-festive forecast of 12 percent. That gap between expectation and result suggests that buyers were more price-sensitive than analysts had assumed, and that the effect of higher component costs on the shelf price was larger than the market had priced in.
The mechanics behind the drop are straightforward. Rising memory costs have been pushing smartphone prices to a new height, and manufacturers have passed much of that increase on to buyers. Counterpoint's data shows that average selling prices, usually abbreviated as ASPs, grew 28 percent year-on-year. That is a very large rise in the average price of a phone in a single year. It also explains why the market looked very different depending on whether it was measured in units or in money: while the number of phones sold fell sharply, market value stayed broadly flat year-on-year, because higher prices largely offset the fall in unit sales.
Discounts, which normally soften price rises during festive sales, were thinner this year. Counterpoint reports that festive discounts narrowed to 10 to 25 percent, compared with 35 to 40 percent in 2025. Even discounted entry-level models were generally priced higher than a year ago, which put upgrades out of reach for many price-sensitive buyers. For a family planning to replace an old handset during Diwali, the combination of a higher sticker price and a smaller discount meant that the same budget stretched much less far than it did twelve months earlier.
Brands responded by leaning on financing. Counterpoint notes that companies relied on no-cost EMIs, bank offers and trade-ins, and that 48 percent of smartphone sales were finance-led. That is close to half of all sales, and it shows how much of the market now depends on spreading payments over time rather than paying upfront. Finance-led selling can keep volumes up in a tough year, but it also reflects a market in which many buyers can only manage a new phone through instalments.
The pattern of the season also changed as it went on. During the first wave, from October 8 to 18, volumes fell 19 percent year-on-year. Online sales, which account for a significant share of smartphone purchases in India, came in below the performance seen during earlier sale events. According to the report, higher consumer traffic failed to translate into actual conversions. In plain terms, many people visited the websites and apps, looked at prices and left without buying.
The brand-by-brand picture shows who coped best. Samsung had the best of the lot, capturing a 21 percent share and overtaking Vivo, as its sales fell 8 percent year-on-year against the 22 percent decline in the overall market. Counterpoint credits strong demand for the Galaxy S25 Ultra and Galaxy S25, as well as better inventory management, noting that Samsung delayed its price hikes until after the sales. Vivo and Oppo declined 21 percent and 24 percent respectively. They held up better in mainline retail, helped by retailer incentives and bundled offers, but were weaker online.
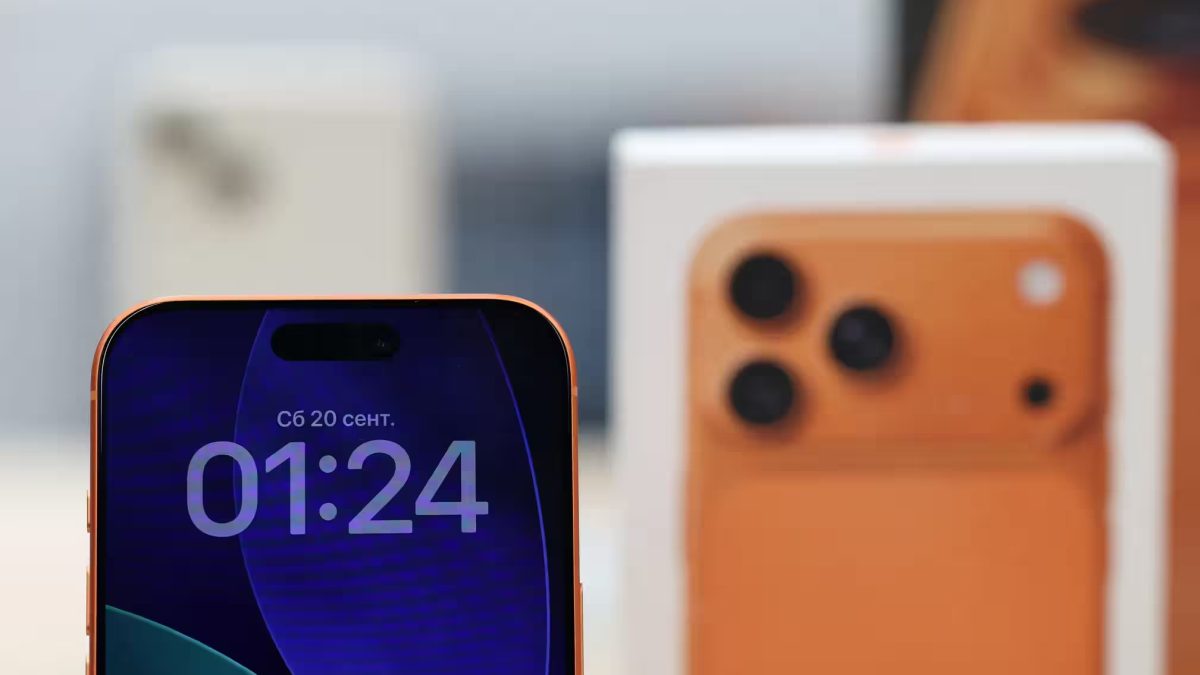
Apple's festive sales declined by double digits year-on-year despite what Counterpoint describes as strong feedback for the new iPhone 18 Pro series and continued consumer interest in the iPhone 17. The report says refurbished iPhones saw strong demand as consumers sought more affordable options, and that this hurt demand for new iPhones. The rise of refurbished phones as a substitute is a telling sign of how price pressure is reshaping behaviour: buyers who want a premium brand but cannot afford a new device are trading down within the brand.
Xiaomi declined sharply, though its sales picked up around Diwali, driven by the Redmi Note 15 and Note 17 series. Google, meanwhile, was the fastest-growing brand in the ultra-premium segment, defined as phones priced above ₹45,000, with Counterpoint saying it sold its highest-ever number of Pixel devices during a festive season. That detail points to a split in the market: at the top end, demand for flagship devices held up, while at the bottom end it did not.
The bottom end was where the damage was worst. Counterpoint reports that brands with exposure to the sub-₹20,000 segment were hit hardest, with sales declining by close to 50 percent. This is the segment that serves first-time smartphone buyers and price-sensitive households, and a drop of that scale means a very large number of people deferred buying a phone this season. The report summarises the season as "value-led rather than volume-led," with premium demand and financing supporting market value while entry-level buyers deferred their purchases.
What does that mean for the industry and for consumers? For manufacturers, it is a reminder that their fortunes depend on component markets they do not control. Memory chips are a core cost in every smartphone, and when their prices rise, the effect flows through to retail price tags. Companies that can absorb part of the increase, or that manage their inventory so they can delay price hikes, can gain share, as Samsung did. Those with thinner margins have less room to manoeuvre, which may explain why brands focused on cheaper phones fared worse.
For consumers, the immediate effect is that upgrading costs more. A buyer who bought a phone for a given amount in 2025 will likely find that a comparable model costs more now and is discounted less. Some will respond by keeping their old phone for longer, some by buying refurbished devices, and some by leaning on financing. All three responses carry trade-offs: older phones receive fewer software updates over time, refurbished devices vary in quality and warranty, and EMIs add to household obligations.
For retailers, the picture is mixed. A season in which value stayed flat but volumes fell means that revenue was supported by higher prices but that footfall and transactions suffered. The report's observation that online traffic did not convert suggests that platforms will have to rethink how they promote phones in a market where shoppers are cautious. Offline retailers, in contrast, seem to have benefited from incentives and bundled offers on some brands.
It is important to be clear about the nature of these figures. They are Counterpoint's estimates, reported by The Hindu, and they cover a specific window from October 8 to November 10. Other research firms may measure the market differently, and final figures can be revised as more data becomes available. The key message, however, is consistent with the broader story of the year: when component costs rise, phones become more expensive, and demand softens, especially among those who can least afford the increase.
Looking ahead, the main question is whether prices will ease or continue to rise. The reports do not forecast memory prices, and it would be speculative to predict them. If component costs remain elevated, manufacturers may continue to raise prices or to trim specifications, and buyers may continue to delay. If costs fall, the market could recover some of the volume it lost this season. Either way, the festive season of 2026 will be remembered as one in which the price of a phone, not the excitement of a sale, set the pace.

Leave a Reply