The Reserve Bank of India has tightened its rules on foreign exchange derivatives since 10 October 2026, in a series of steps meant to reduce speculative dollar buying and keep the rupee’s moves orderly. Governor Sanjay Malhotra said on 14 October that the central bank is open to further measures if they are needed, according to reports.
The first measure was a 20% cash reserve requirement for banks on certain foreign exchange derivatives that clients use to hedge current-account exposures. It was later extended to all rupee-linked foreign exchange derivatives in which authorised banks buy foreign currency against the rupee. A cash reserve requirement obliges a bank to keep a share of such positions as reserves, which raises the cost of offering the product.
Other steps followed. Reports describe restrictions on rebooking cancelled foreign exchange derivative contracts, a 20% Foreign Exchange Risk Reserve for specified transactions, tighter documentation requirements and a cut in the limit for certain derivative positions without an underlying exposure from $100 million to $5 million. One report that covered the measures did not mention the $100 million to $5 million limit or the risk reserve, so those details come from a different report and should be confirmed in the RBI’s circulars.
The central bank also directed oil companies to meet their dollar requirements through a special facility. Oil marketing companies are among the largest buyers of dollars in the market because of crude imports, so routing their demand through a dedicated channel removes a large and predictable source of demand from the open market.
Why did the RBI act? Malhotra pointed to excessive dollar-buying positions. He said the central bank found that a large number of trades were being cancelled and rebooked on the same day, and that around one-third of trades were closed or cancelled on the day they were entered into. That pattern suggests that some participants were taking short-term bets on the rupee, rather than hedging real exposures.
The Governor was clear on how the measures should be understood. He said they are not capital controls, and that their purpose is to ensure that foreign exchange transactions are used for genuine hedging needs and not for speculative positions. A capital control would restrict the movement of money across borders, while these rules target the use of derivatives.
The rupee has responded. It closed at 95.17 against the dollar on 14 October, up 19 paise on the day, and the central bank has also intervened directly in the market. These moves followed a period of weakness caused by expensive crude oil and heavy foreign selling of Indian shares.
The measures are part of a wider set of pressures. The central bank raised the repo rate to 5.50% on 7 October, retail inflation was 5.54% in September, and one analysis says the RBI sold $29.6 billion of foreign exchange in March, the highest in 13 months. A weaker rupee raises the cost of imports and adds to inflation, which is why the central bank treats the exchange rate as relevant to price stability as well as financial stability.
For companies, the changes mean higher costs and more paperwork for hedging. Firms with genuine foreign currency exposures will still be able to hedge, but they may pay more and have to show their underlying transactions. For traders, the scope for short-term speculation is narrower.
The effect will be judged over the coming weeks. If the rupee stabilises and the pattern of same-day cancellations fades, the central bank may not need to do more, and Malhotra has indicated that it is ready to if it does.
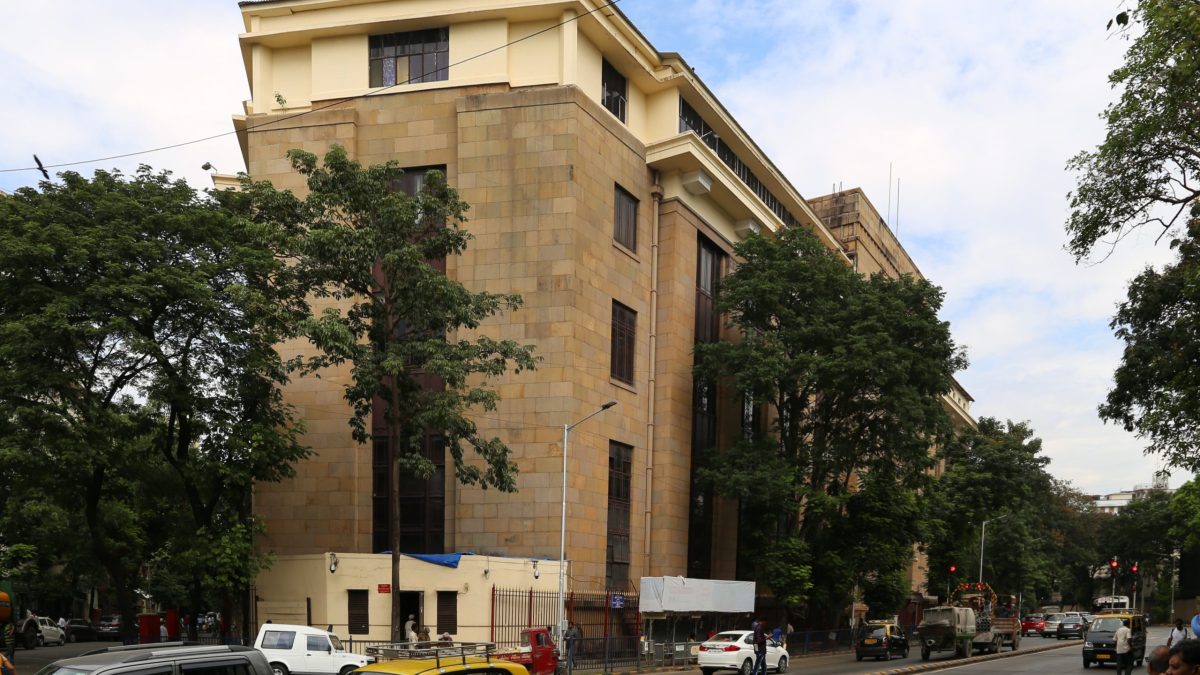
Featured image: A Reserve Bank of India office building in Mumbai (file photo). Photo by Sailko, licensed under CC BY 3.0, via Wikimedia Commons.

Leave a Reply